Hamilton County mortgage lender
Your first home starts with a text. Send Dillon the address and he'll tell you what it takes to buy it, in plain English, and he'll answer you himself. He lends across Hamilton County, from Carmel and Fishers to Westfield, Noblesville and the towns north, into Zionsville and Indianapolis, and everywhere else in Indiana.
A mortgage lender who explains the whole thing
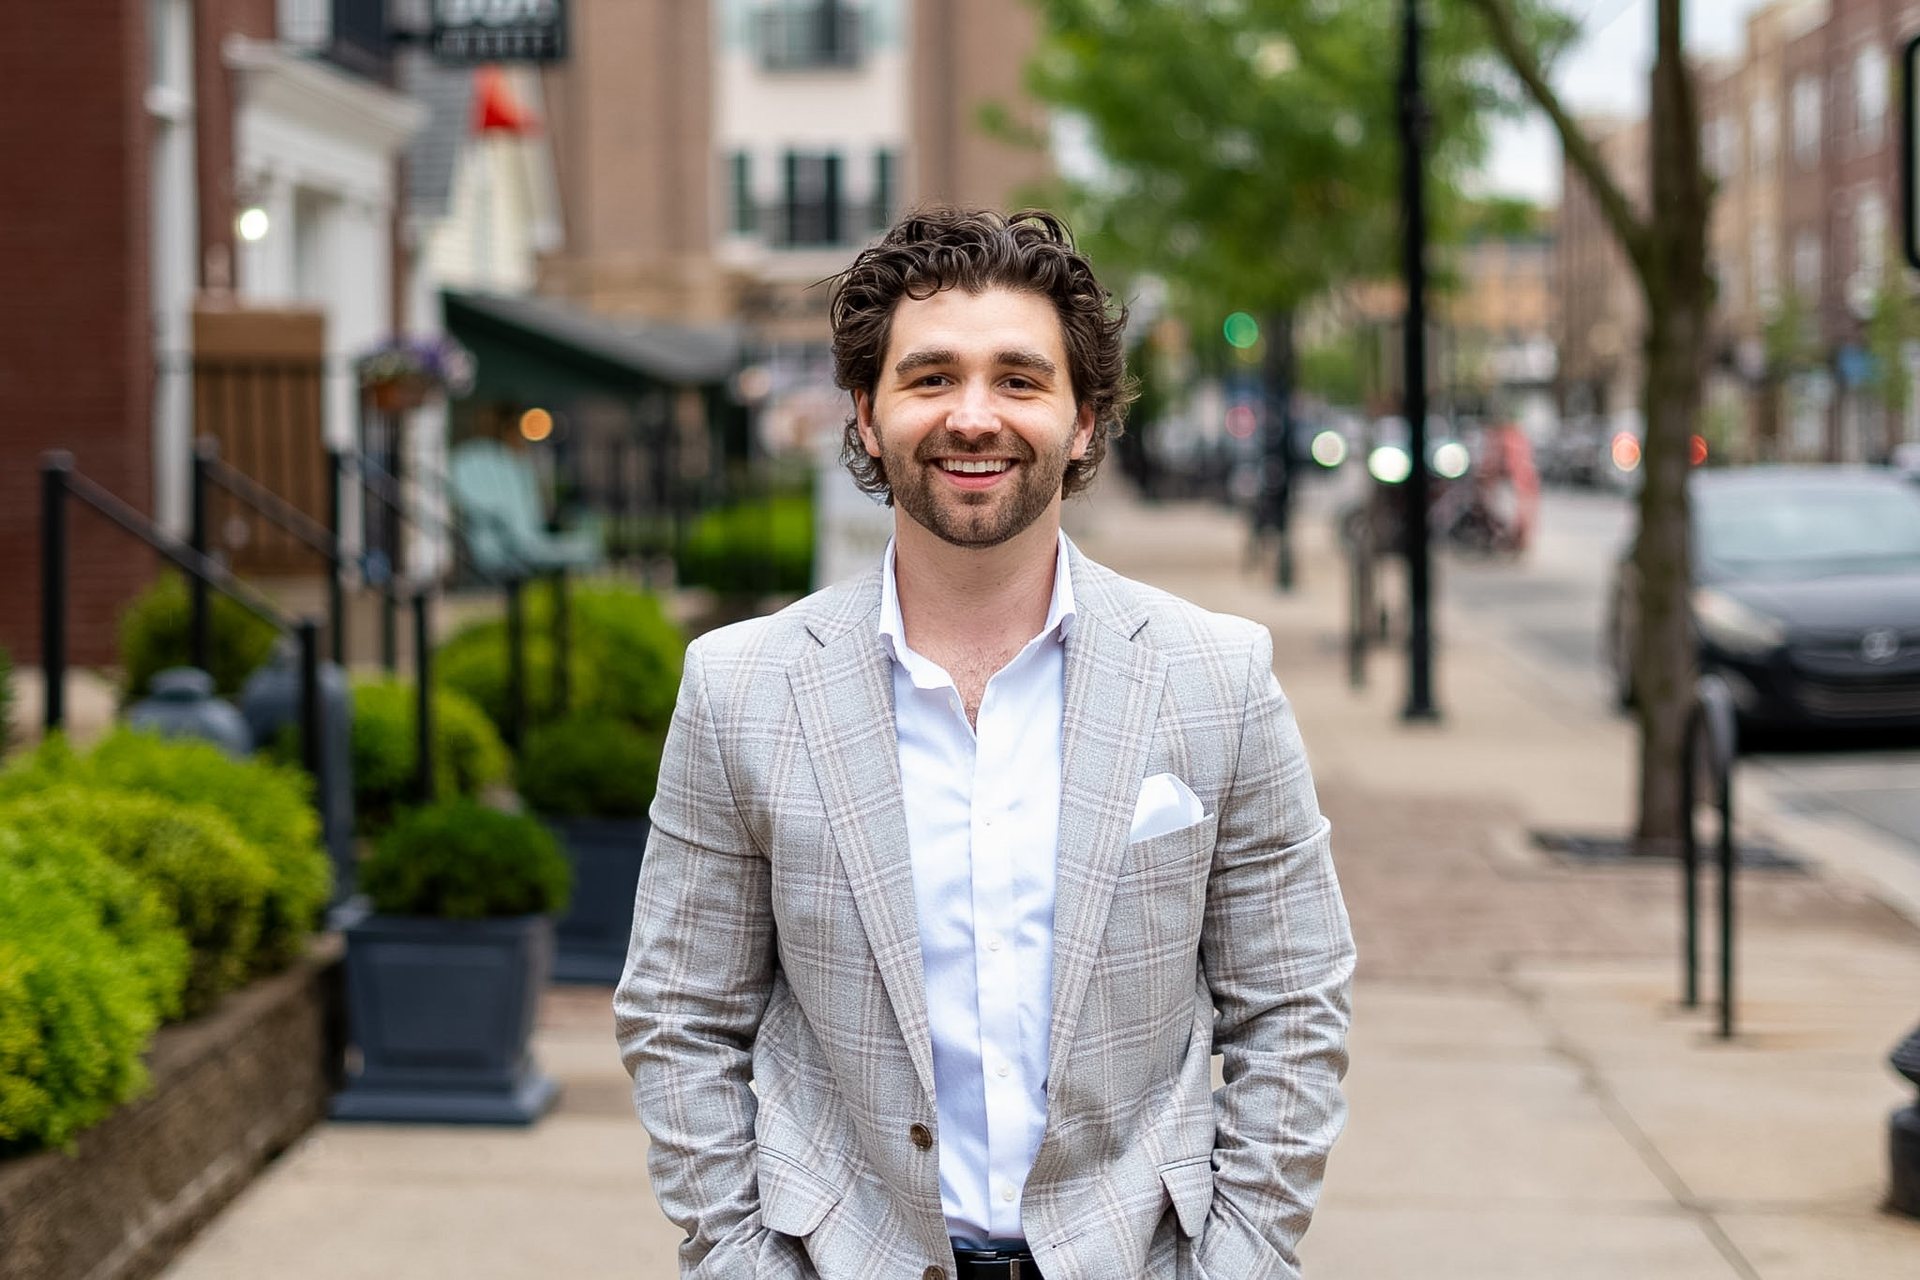
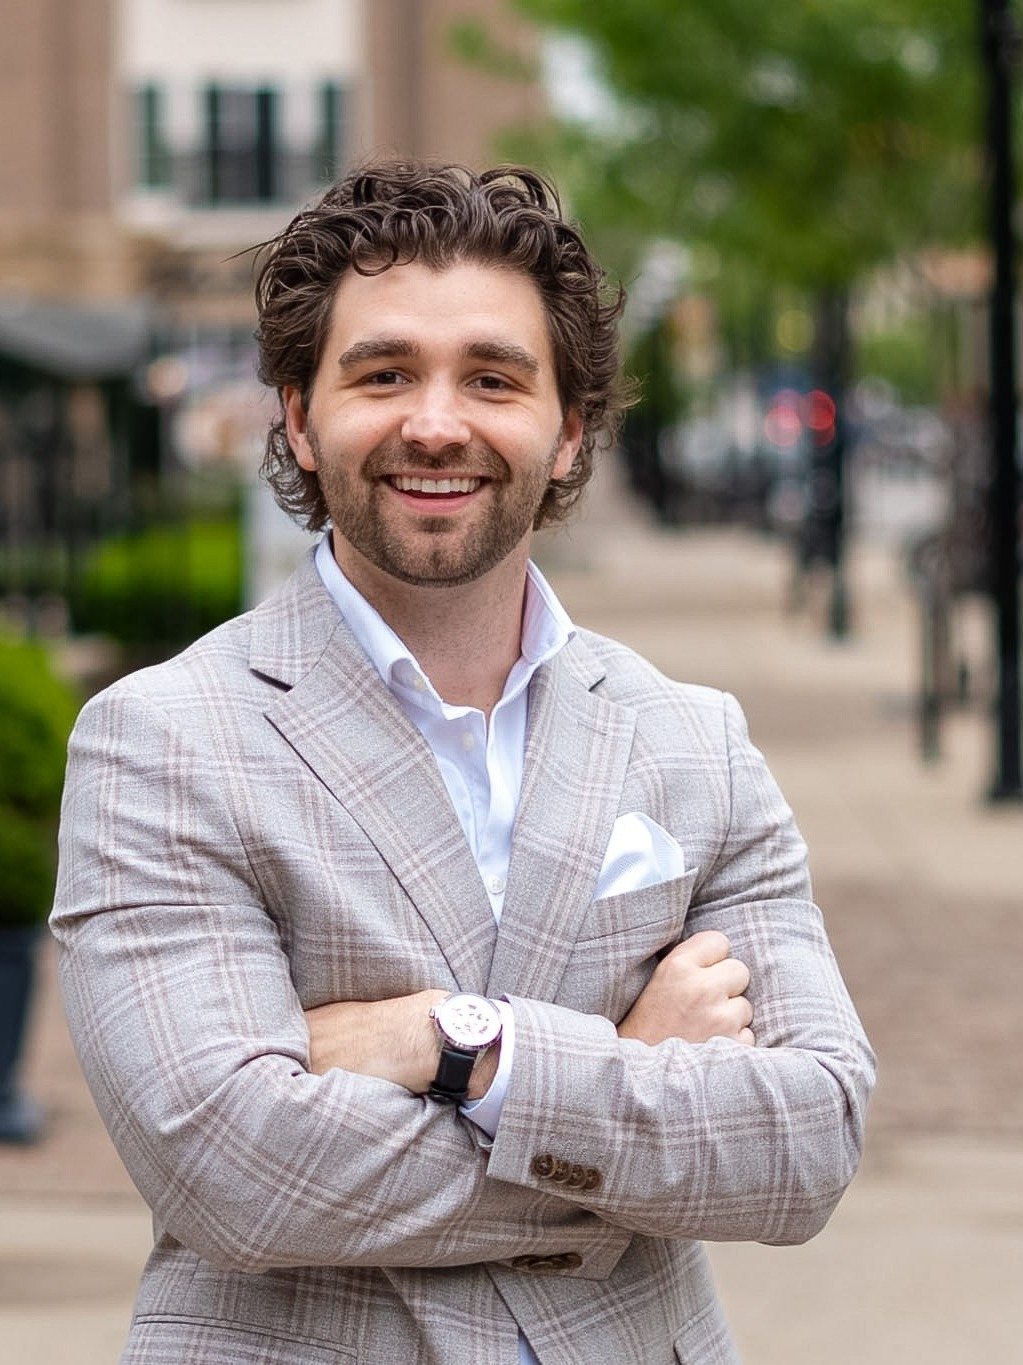
Dillon Baker is a residential mortgage lender at Rate. His office is at 252 W Main St in Carmel, his files run the length of Hamilton County and out across the state, and he is licensed to lend anywhere in Indiana. He works with first time buyers, self employed and 1099 borrowers, and the real estate agents who send them.
The way he puts it: "I treat lending as teaching." A buyer who understands the math of the move makes a better decision than one who was handed a number, so every conversation starts with what the loan actually costs to carry, which documents matter, and what happens next. Plain English, no jargon-dropping.
The process is short on purpose. One document checklist, one credit pull, a Microsoft Teams intro call if you want one, and a pre-approval letter that holds up with agents and sellers. Dillon flags underwriting issues early instead of the day before closing, which is why his past files have averaged about 12 days from contract to clear to close. No surprises at the table.
He doesn't do commercial lending, business loans, auto loans or unsecured personal loans. He does residential mortgages in Indiana, and he answers his own phone.
Twelve loan programs, in plain words
What his buyers say on Google
Every quote here is verbatim from Dillon's Google profile, carrying the reviewer's own name. Between them the photographs are his own, from a class, a desk and Main Street in Carmel.
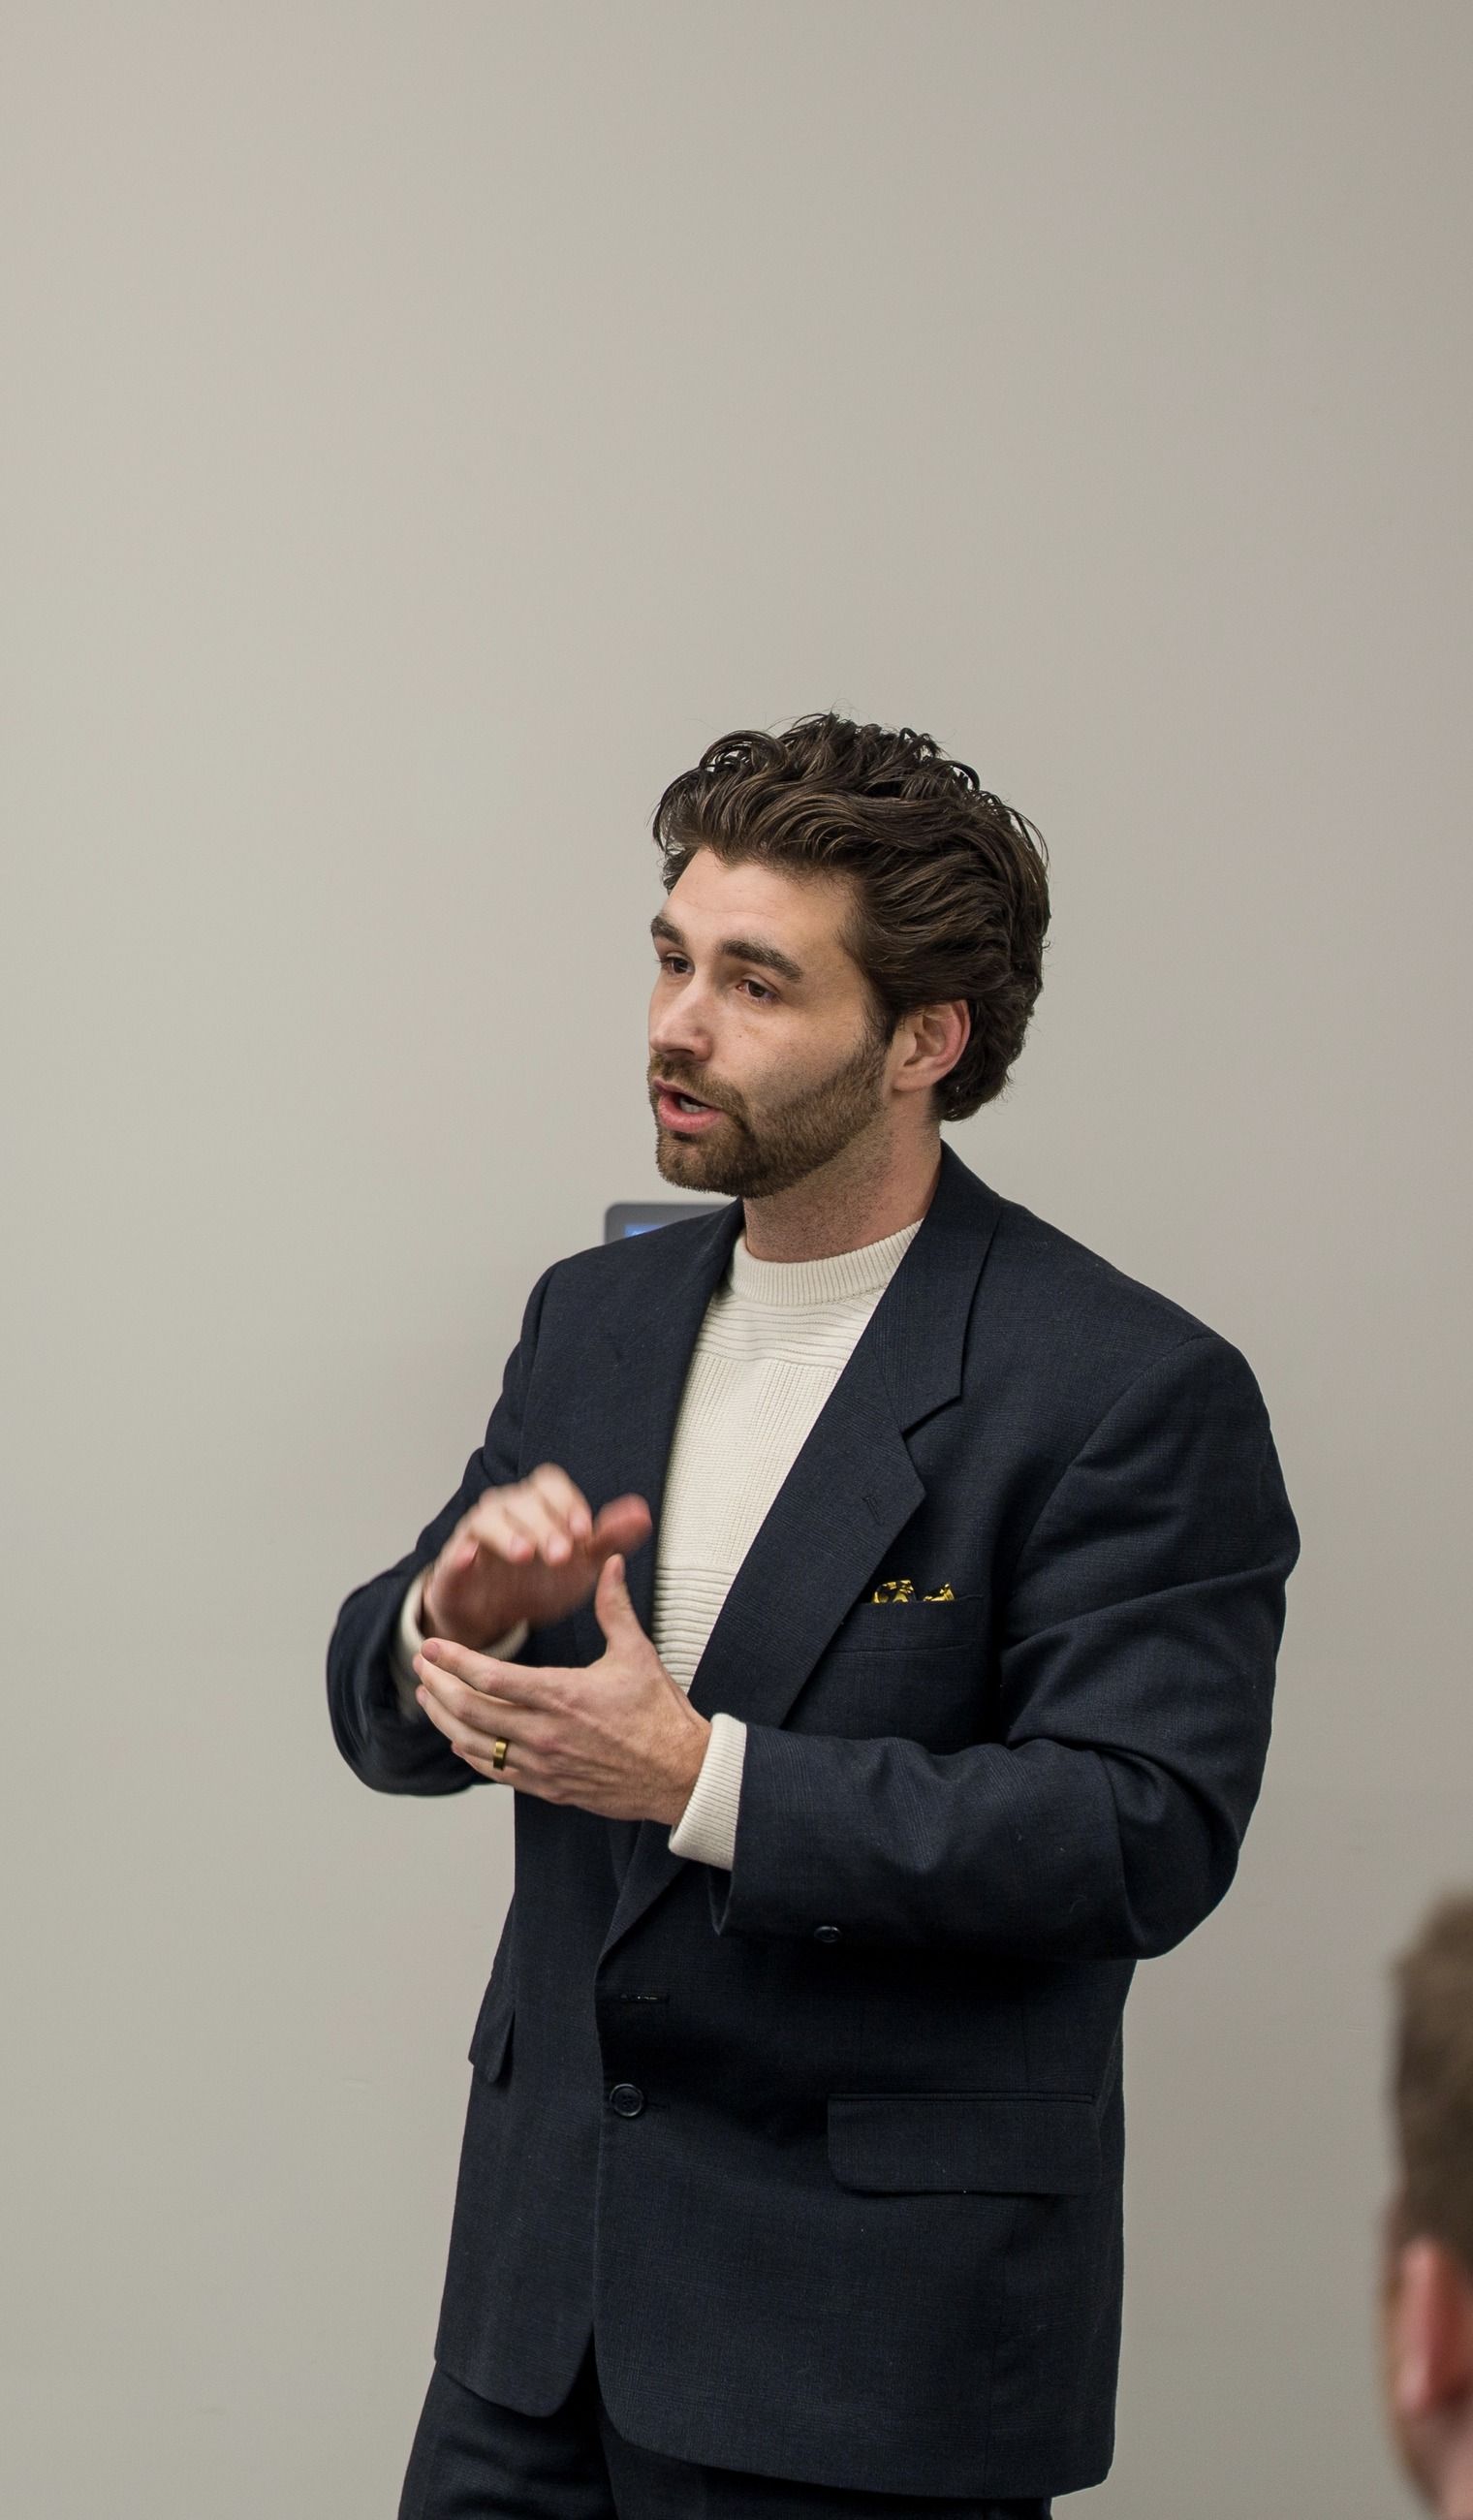
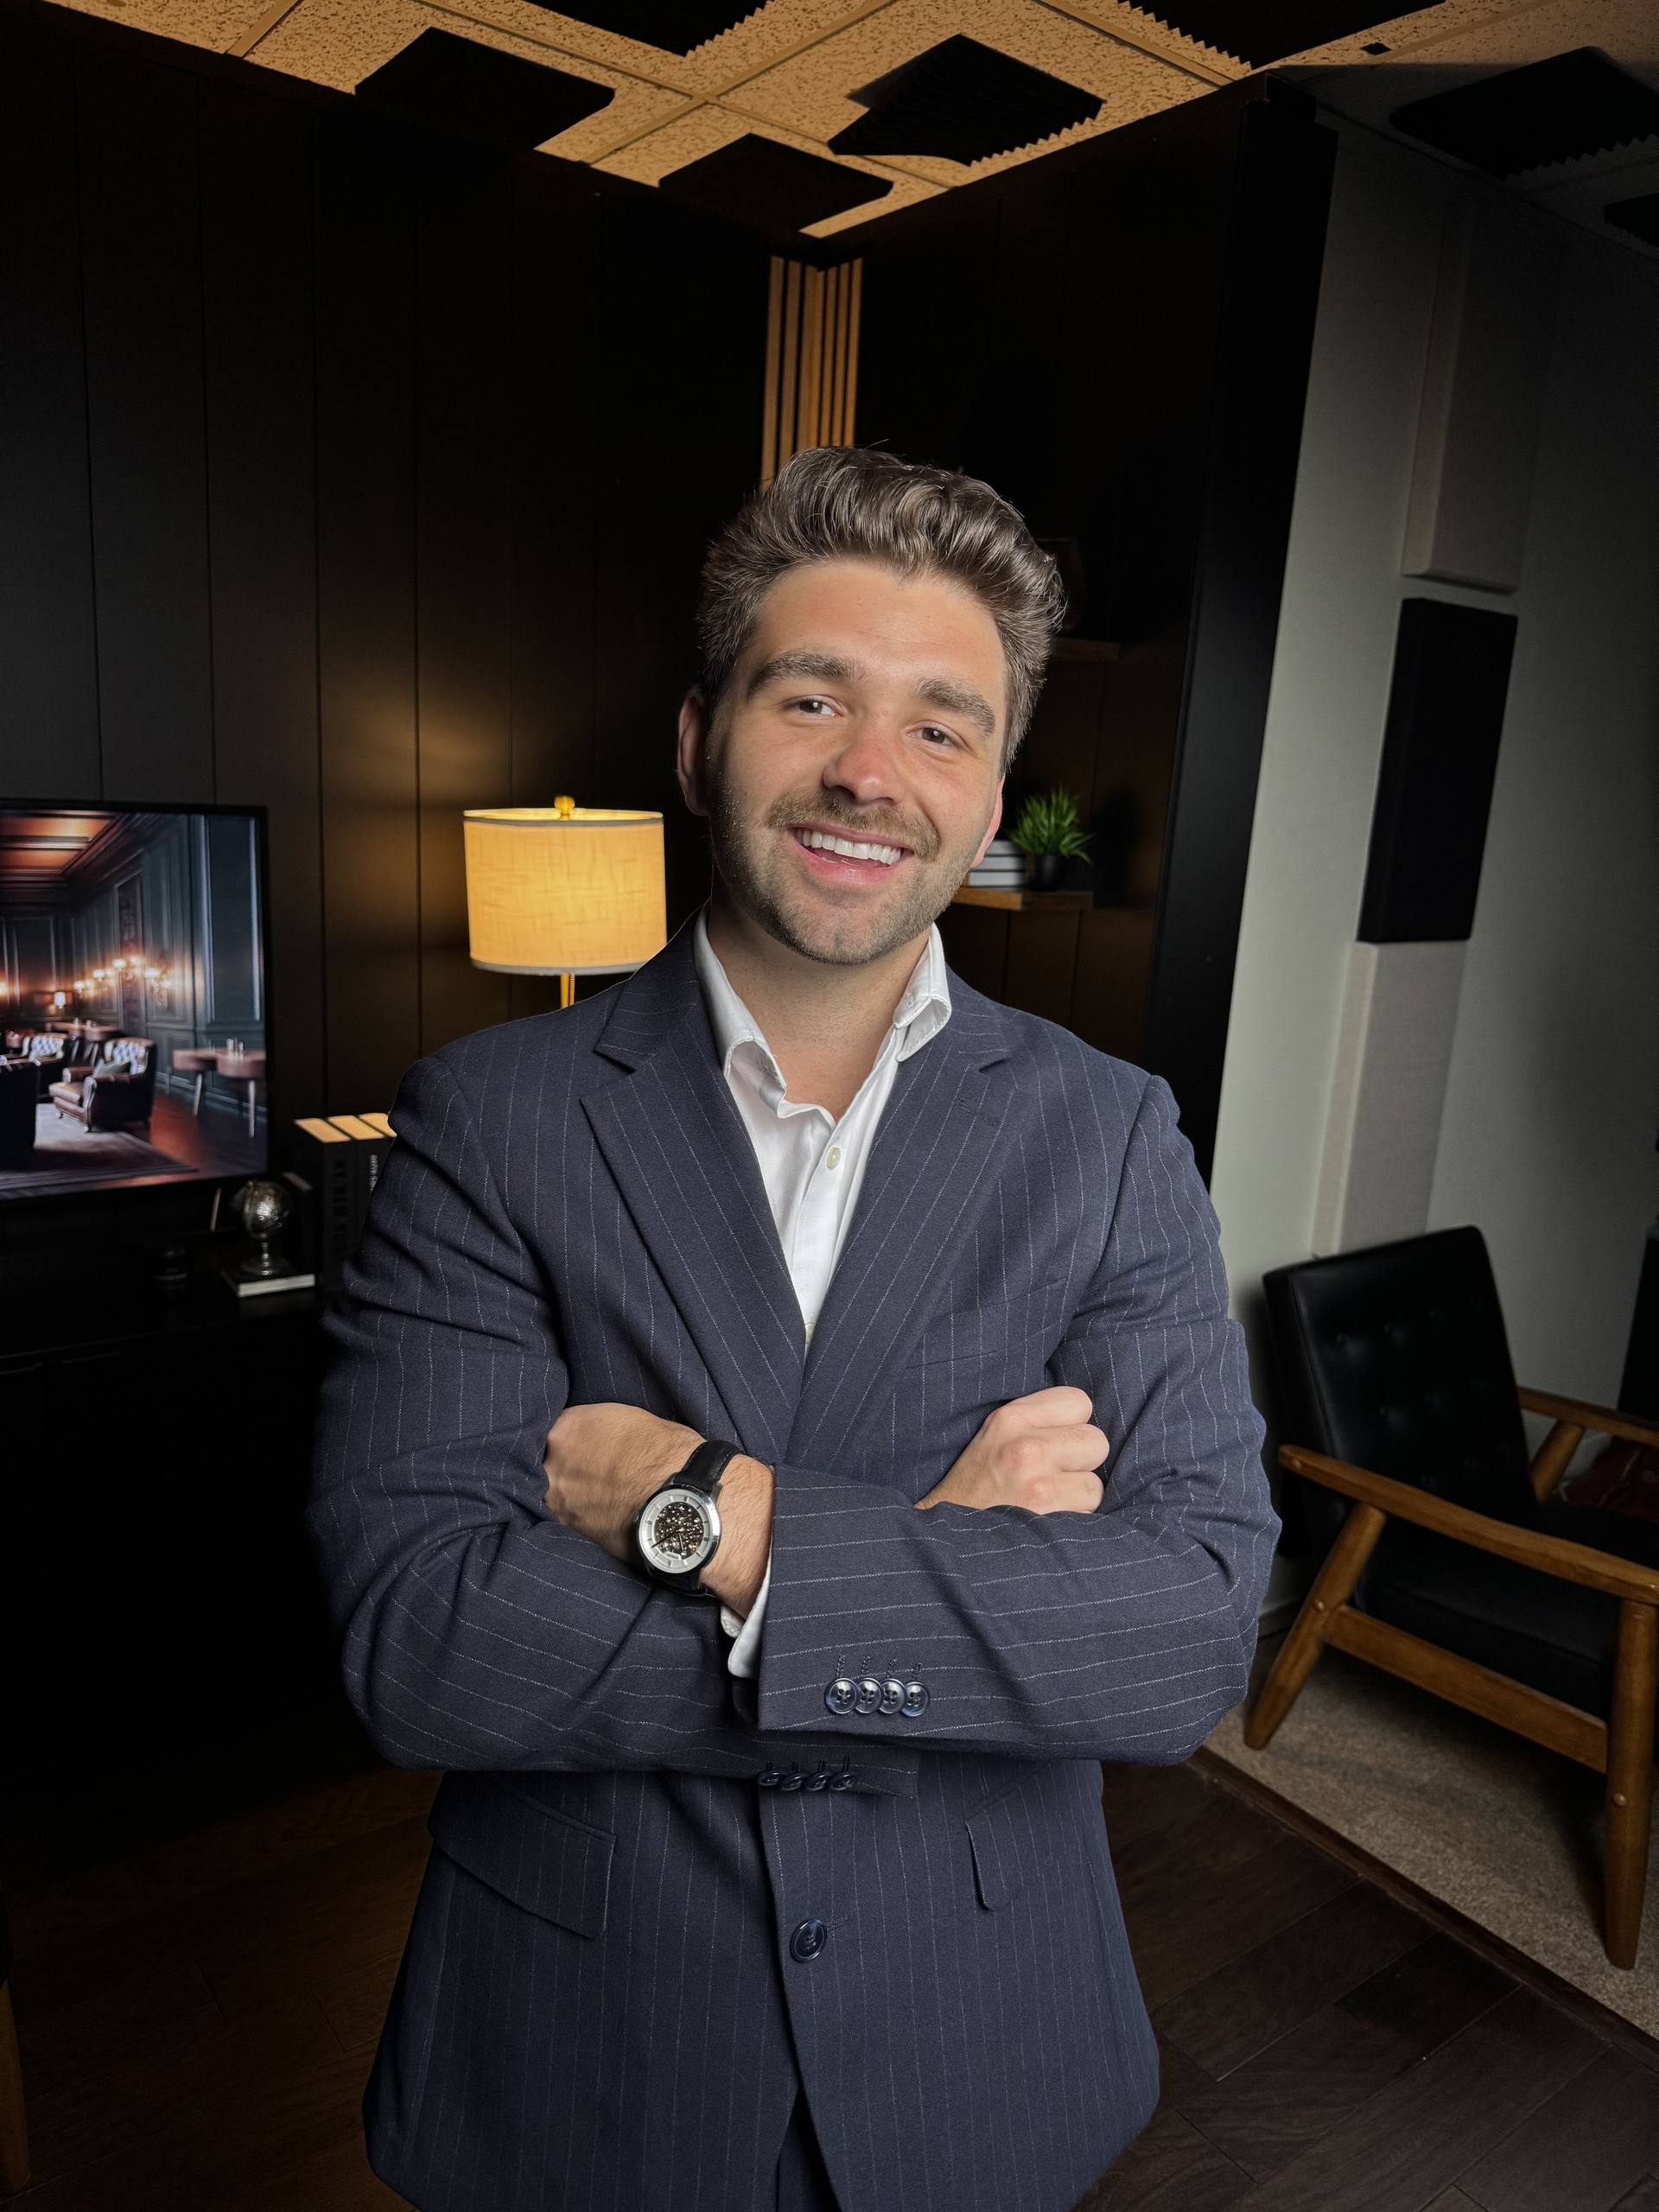
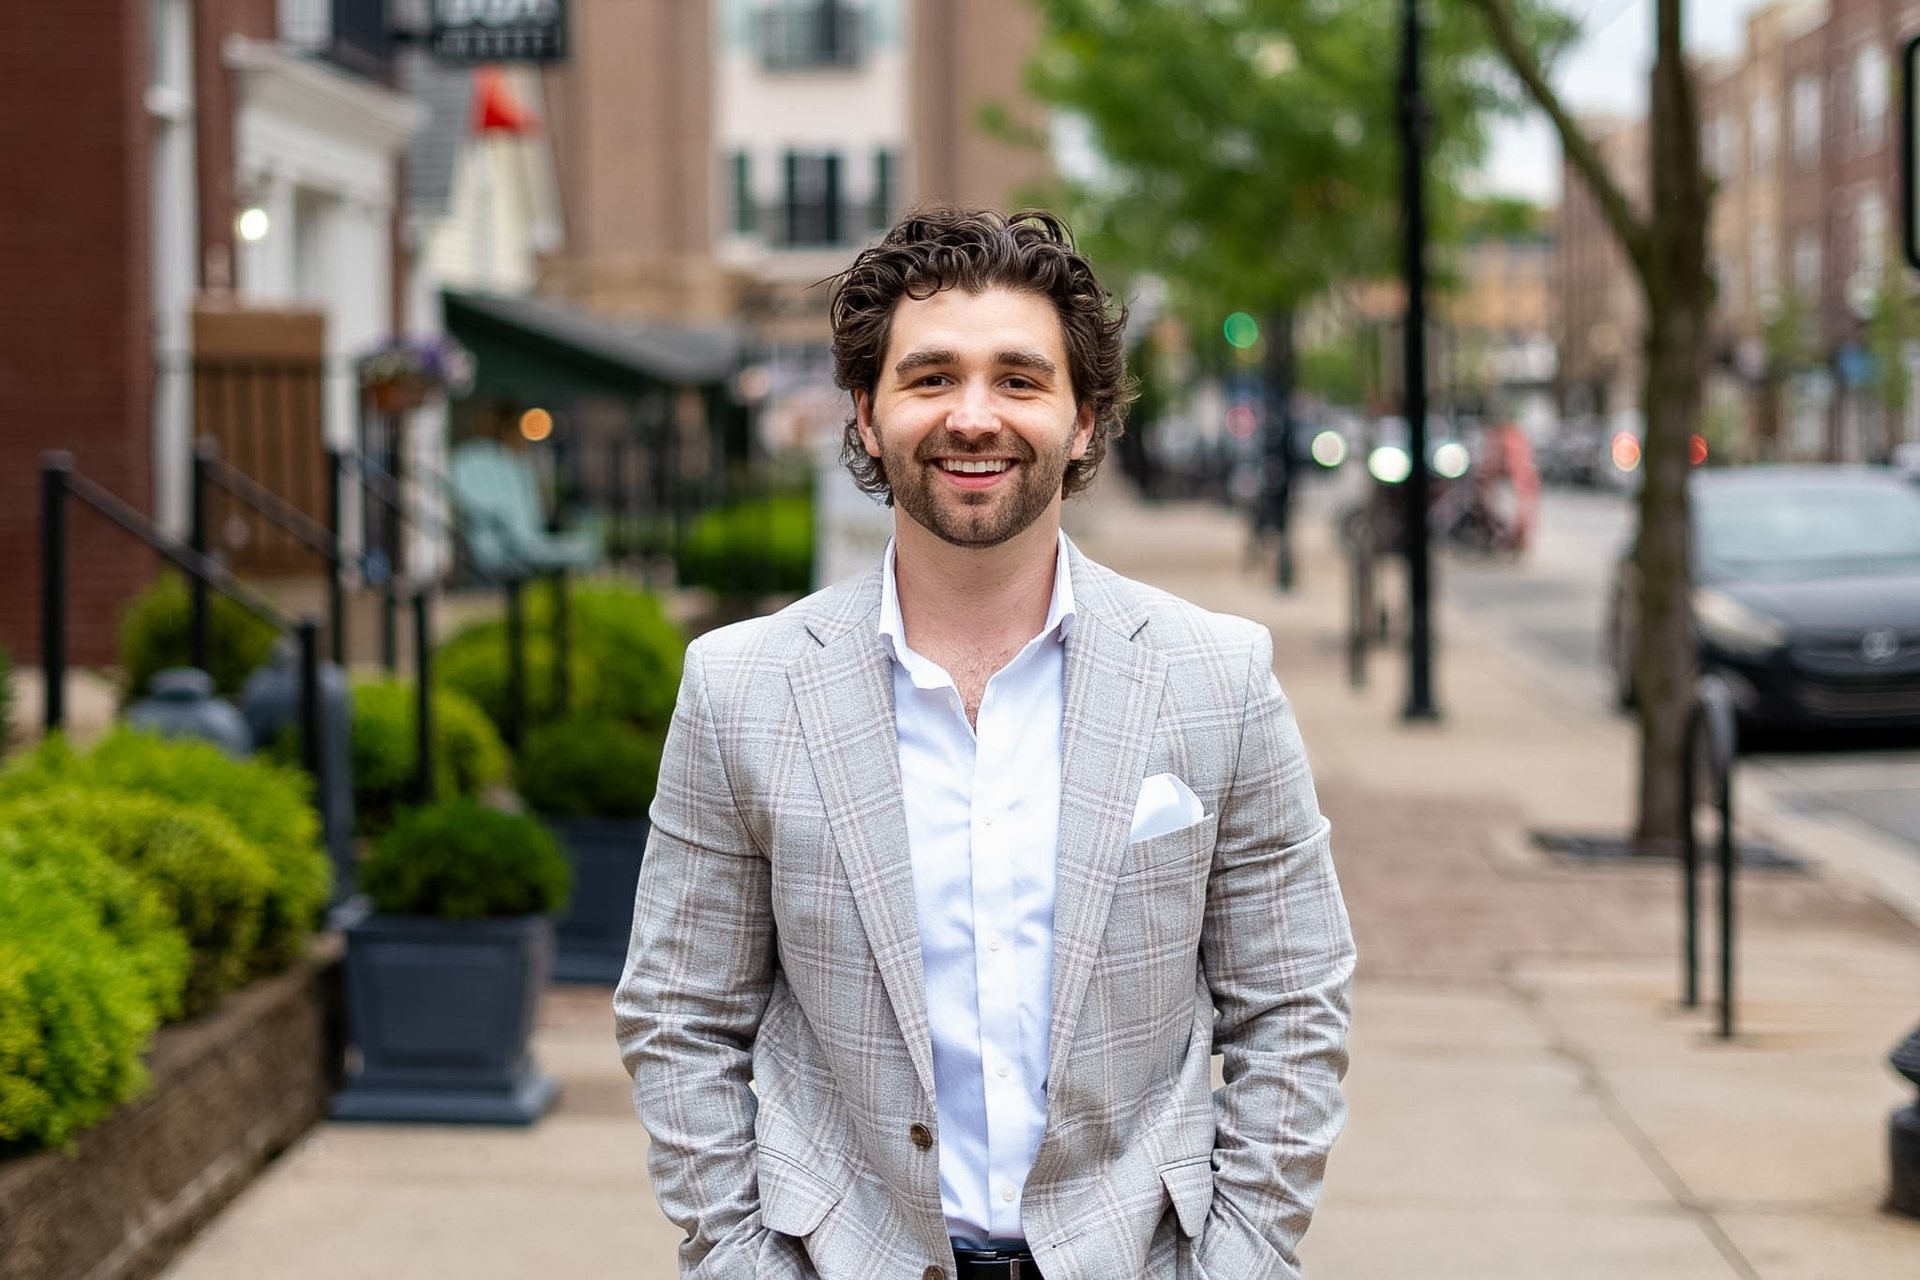
Every review, in full, is on Dillon's Google profile. 5.0 from 9 reviews, read September 15, 2026.
How a loan with Dillon goes
Every loan Dillon closes starts the same way: a text to 317-847-6869, answered by him. Offers don't wait for business hours, so evenings and weekends count. From there it runs in seven steps, and you hear from him at each one.
The whole thing is built so you always know where you stand. "I flag underwriting issues early instead of the day before closing."
Hey Dillon, we're looking at houses in Fishers and want to know what we can afford.
Great. Send me your name and your cell number and I'll text you a short document checklist. One list, one credit pull, that's it.
Fifteen minutes on Teams or the phone. I walk you through the options in plain English and we settle on a program that fits your season of life.
Same day, often inside an hour. You get a pre-approval letter that holds up with agents and sellers, so your offer means something.
Found one? Text me the listing. I run the numbers on that exact house before you write the offer, so you know the math of the move.
I flag anything underwriting will ask about early, not the day before closing. My past files have averaged about 12 days from contract to clear to close.
Buyer gets their keys. Then you hear from me after closing too, with a newsletter and a check in when it's worth reviewing the loan.
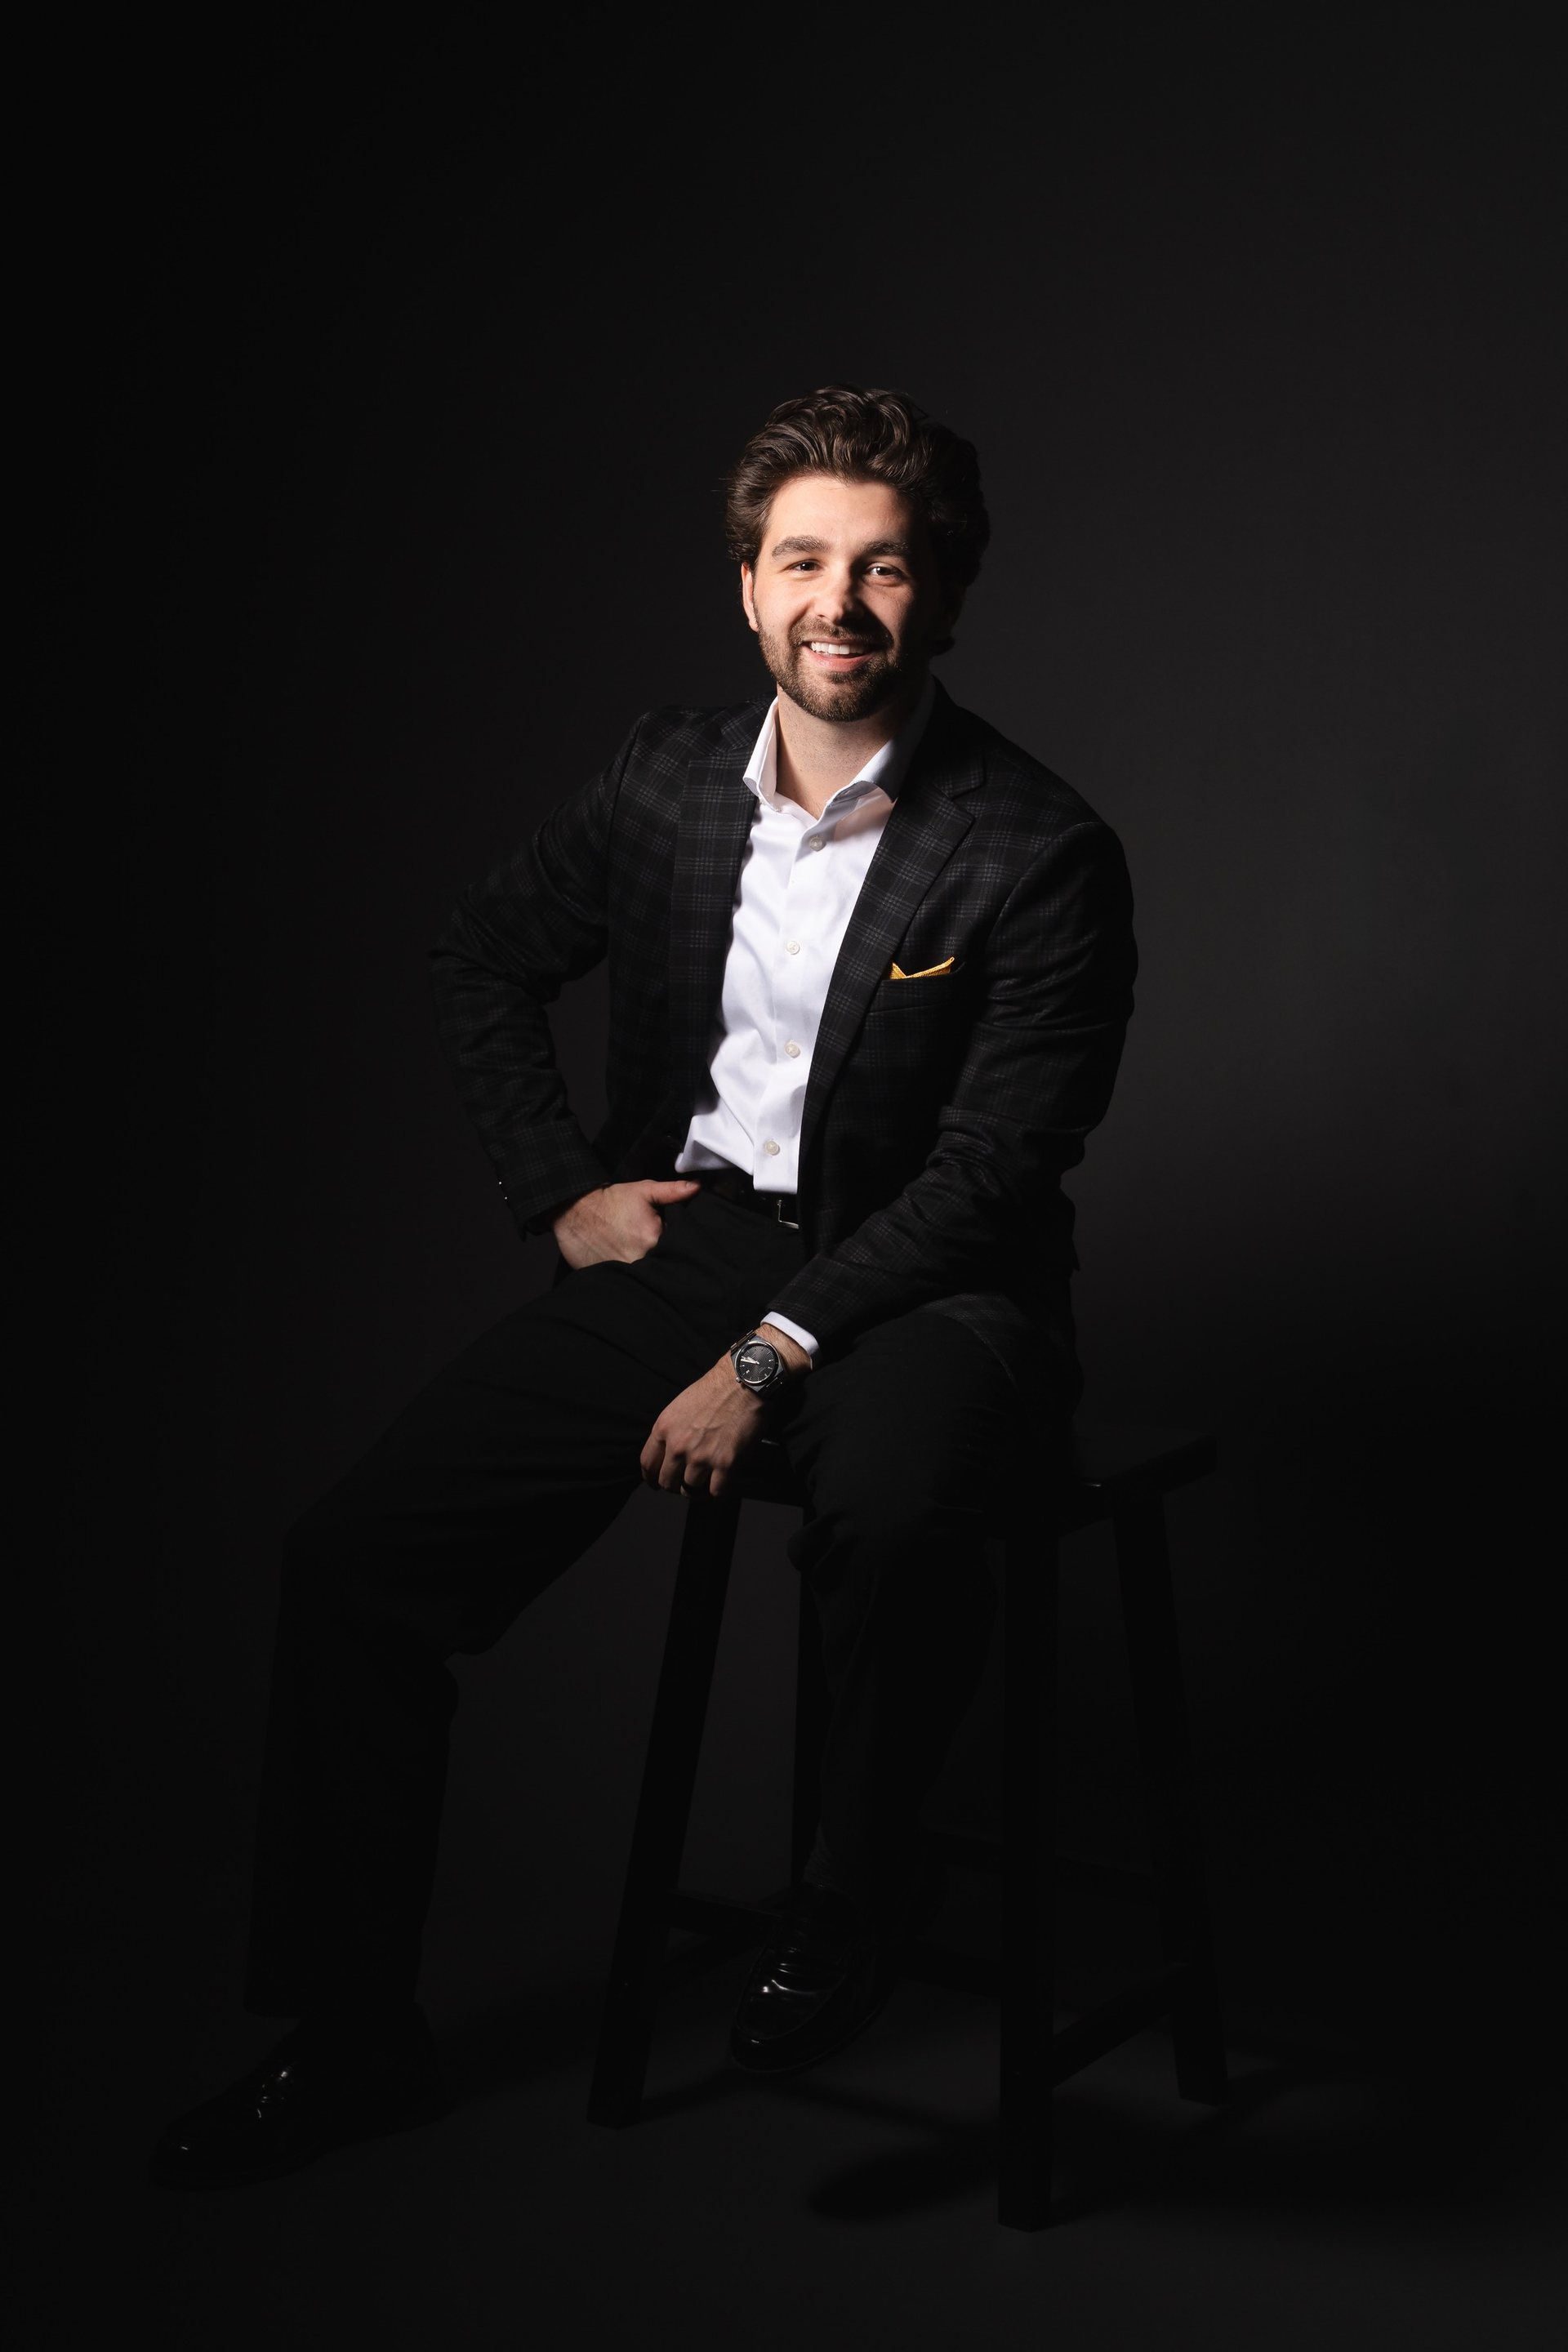
First time buyers get a guide, not a quote
Most of the people Dillon works with are buying their first home in Hamilton County or Indianapolis, and most of them have never been told how a mortgage actually works. So the first meeting is a lesson, not a sales call: an education first process that covers down payment options, what a pre-approval does to your credit, and what the monthly cost really includes.
A house is more than four walls. It's an anchor, an asset, and often the first real step toward generational wealth, which is exactly why the decision deserves a straight explanation. These are the four questions first time buyers ask Dillon most, with his answers.
How much do I actually need for a down payment?
Less than most people think, and it depends on the program. Conventional and FHA loans both offer low down payment options, eligible VA and USDA borrowers can buy with no down payment, and there are down payment assistance programs through Rate for buyers who qualify. Dillon will show you the real number for your situation, on the house you're looking at, in writing.
Should I wait for rates to drop?
Timing the market perfectly is nearly impossible. What Dillon can do is show you the math of the move on today's numbers, so you decide with the facts in front of you. Some buyers choose buying now with a plan to refinance later; some choose to wait. Both are reasonable when you understand the trade.
Does a pre-approval hurt my credit?
A mortgage pre-approval is one credit pull, and the credit bureaus treat several mortgage inquiries inside a short shopping window as one event. Dillon does one document checklist and one credit pull, and you get a pre-approval letter that holds up with agents and sellers.
What will you need from me?
Recent pay stubs, two years of W-2s or tax returns, two months of bank statements, and your ID. Self employed buyers use bank statements instead of tax returns on some programs. Dillon texts you the exact list for your program so nothing is a surprise.
Send me your buyer. I'll send back a plan.Dillon Baker, VP of Mortgage Lending at Rate
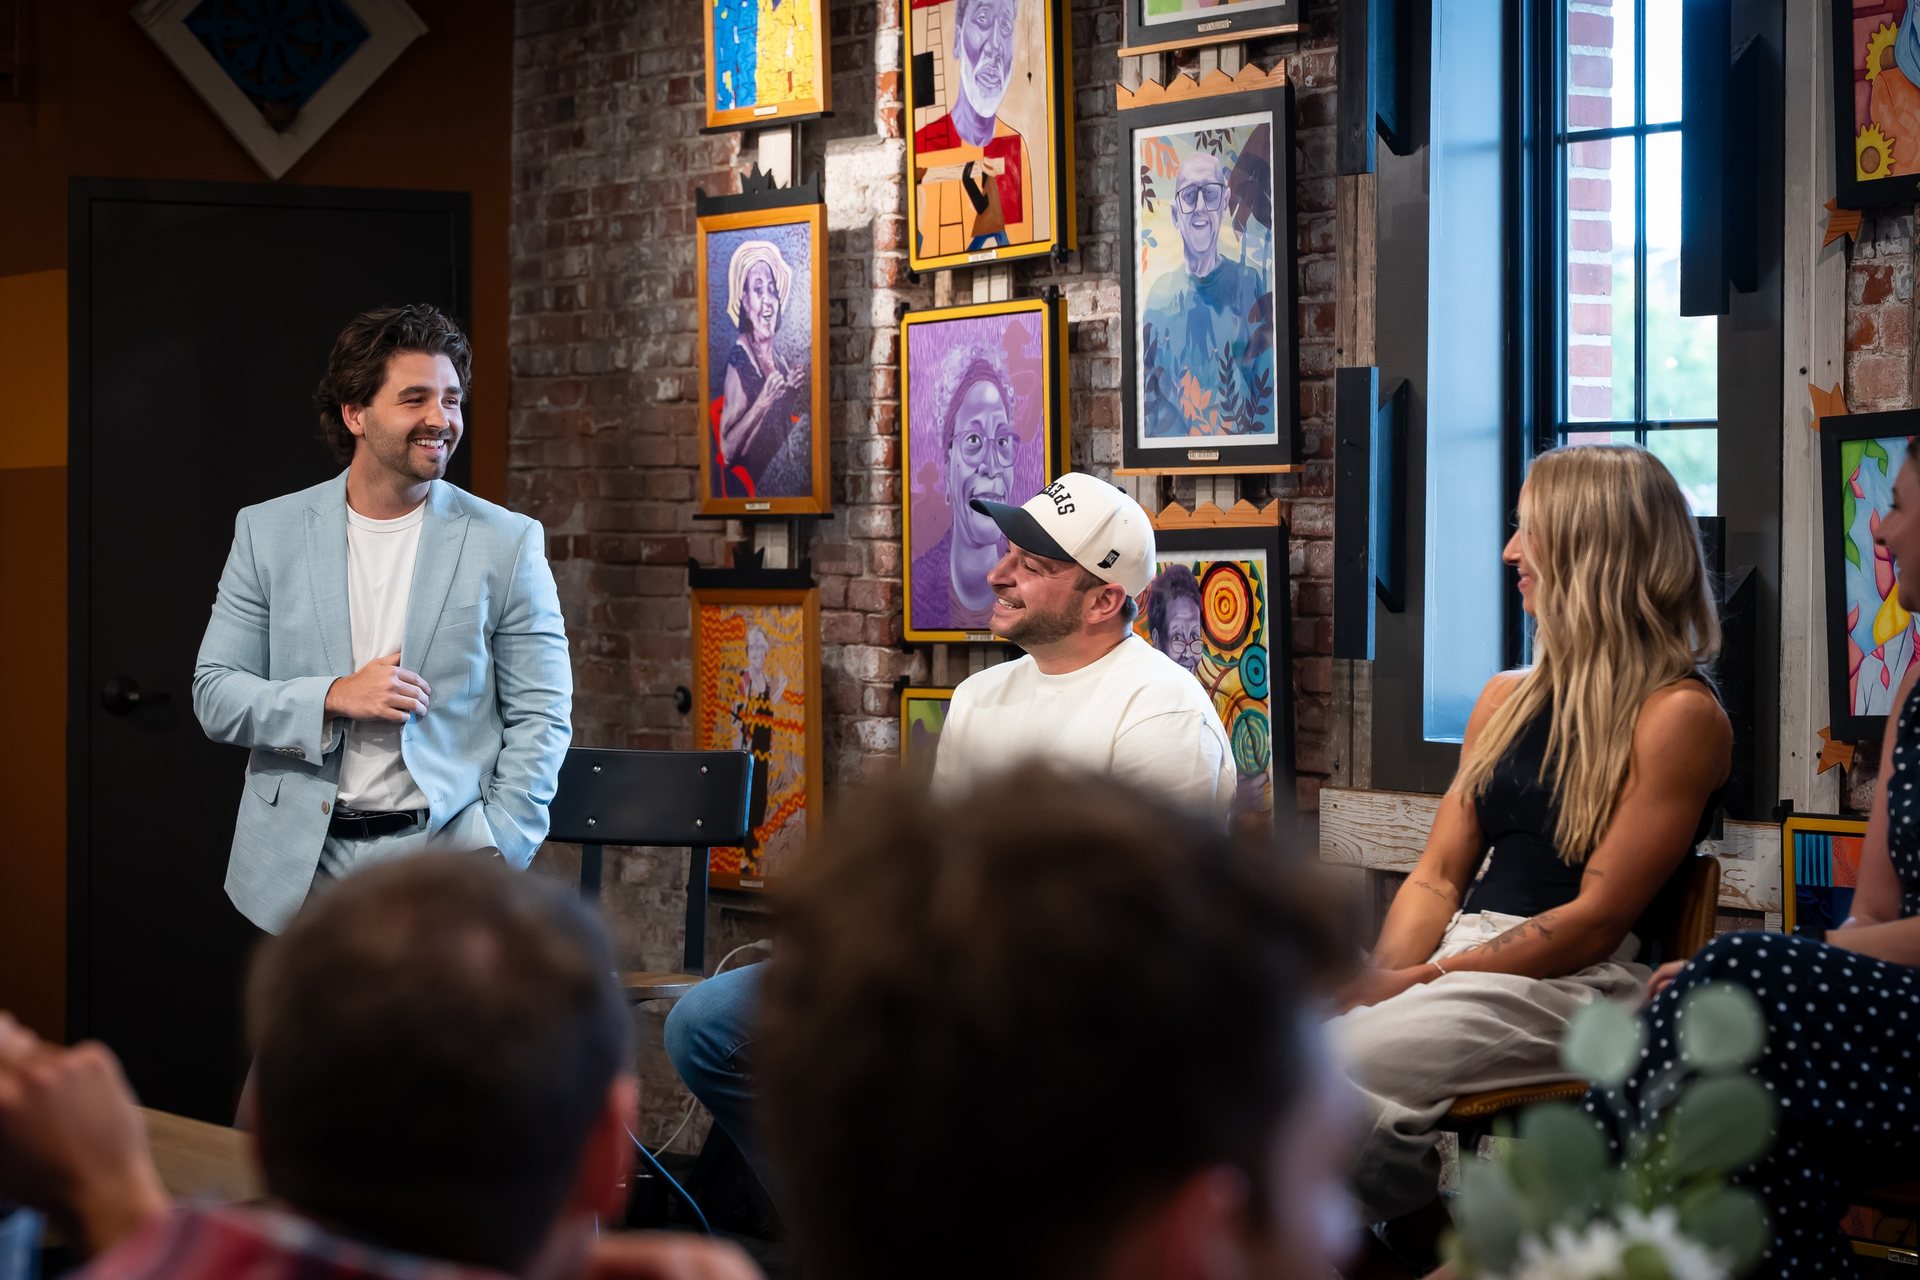
A lender your buyers will thank you for
Agents work with Dillon because he is fast, communicative, and makes them look good in front of their clients. Same day pre-approvals for your buyer, updates in writing at every milestone, and a pre-approval letter listing agents actually trust. One agent put it this way on Google: "What I appreciated the most was how fast he was to respond to both myself and the client."
Agent referred buyers who need a same day pre-approval get priority. Dillon also hosts homebuyer education classes that are open to any agent and the public, so your clients can learn the process before they fall in love with a house.
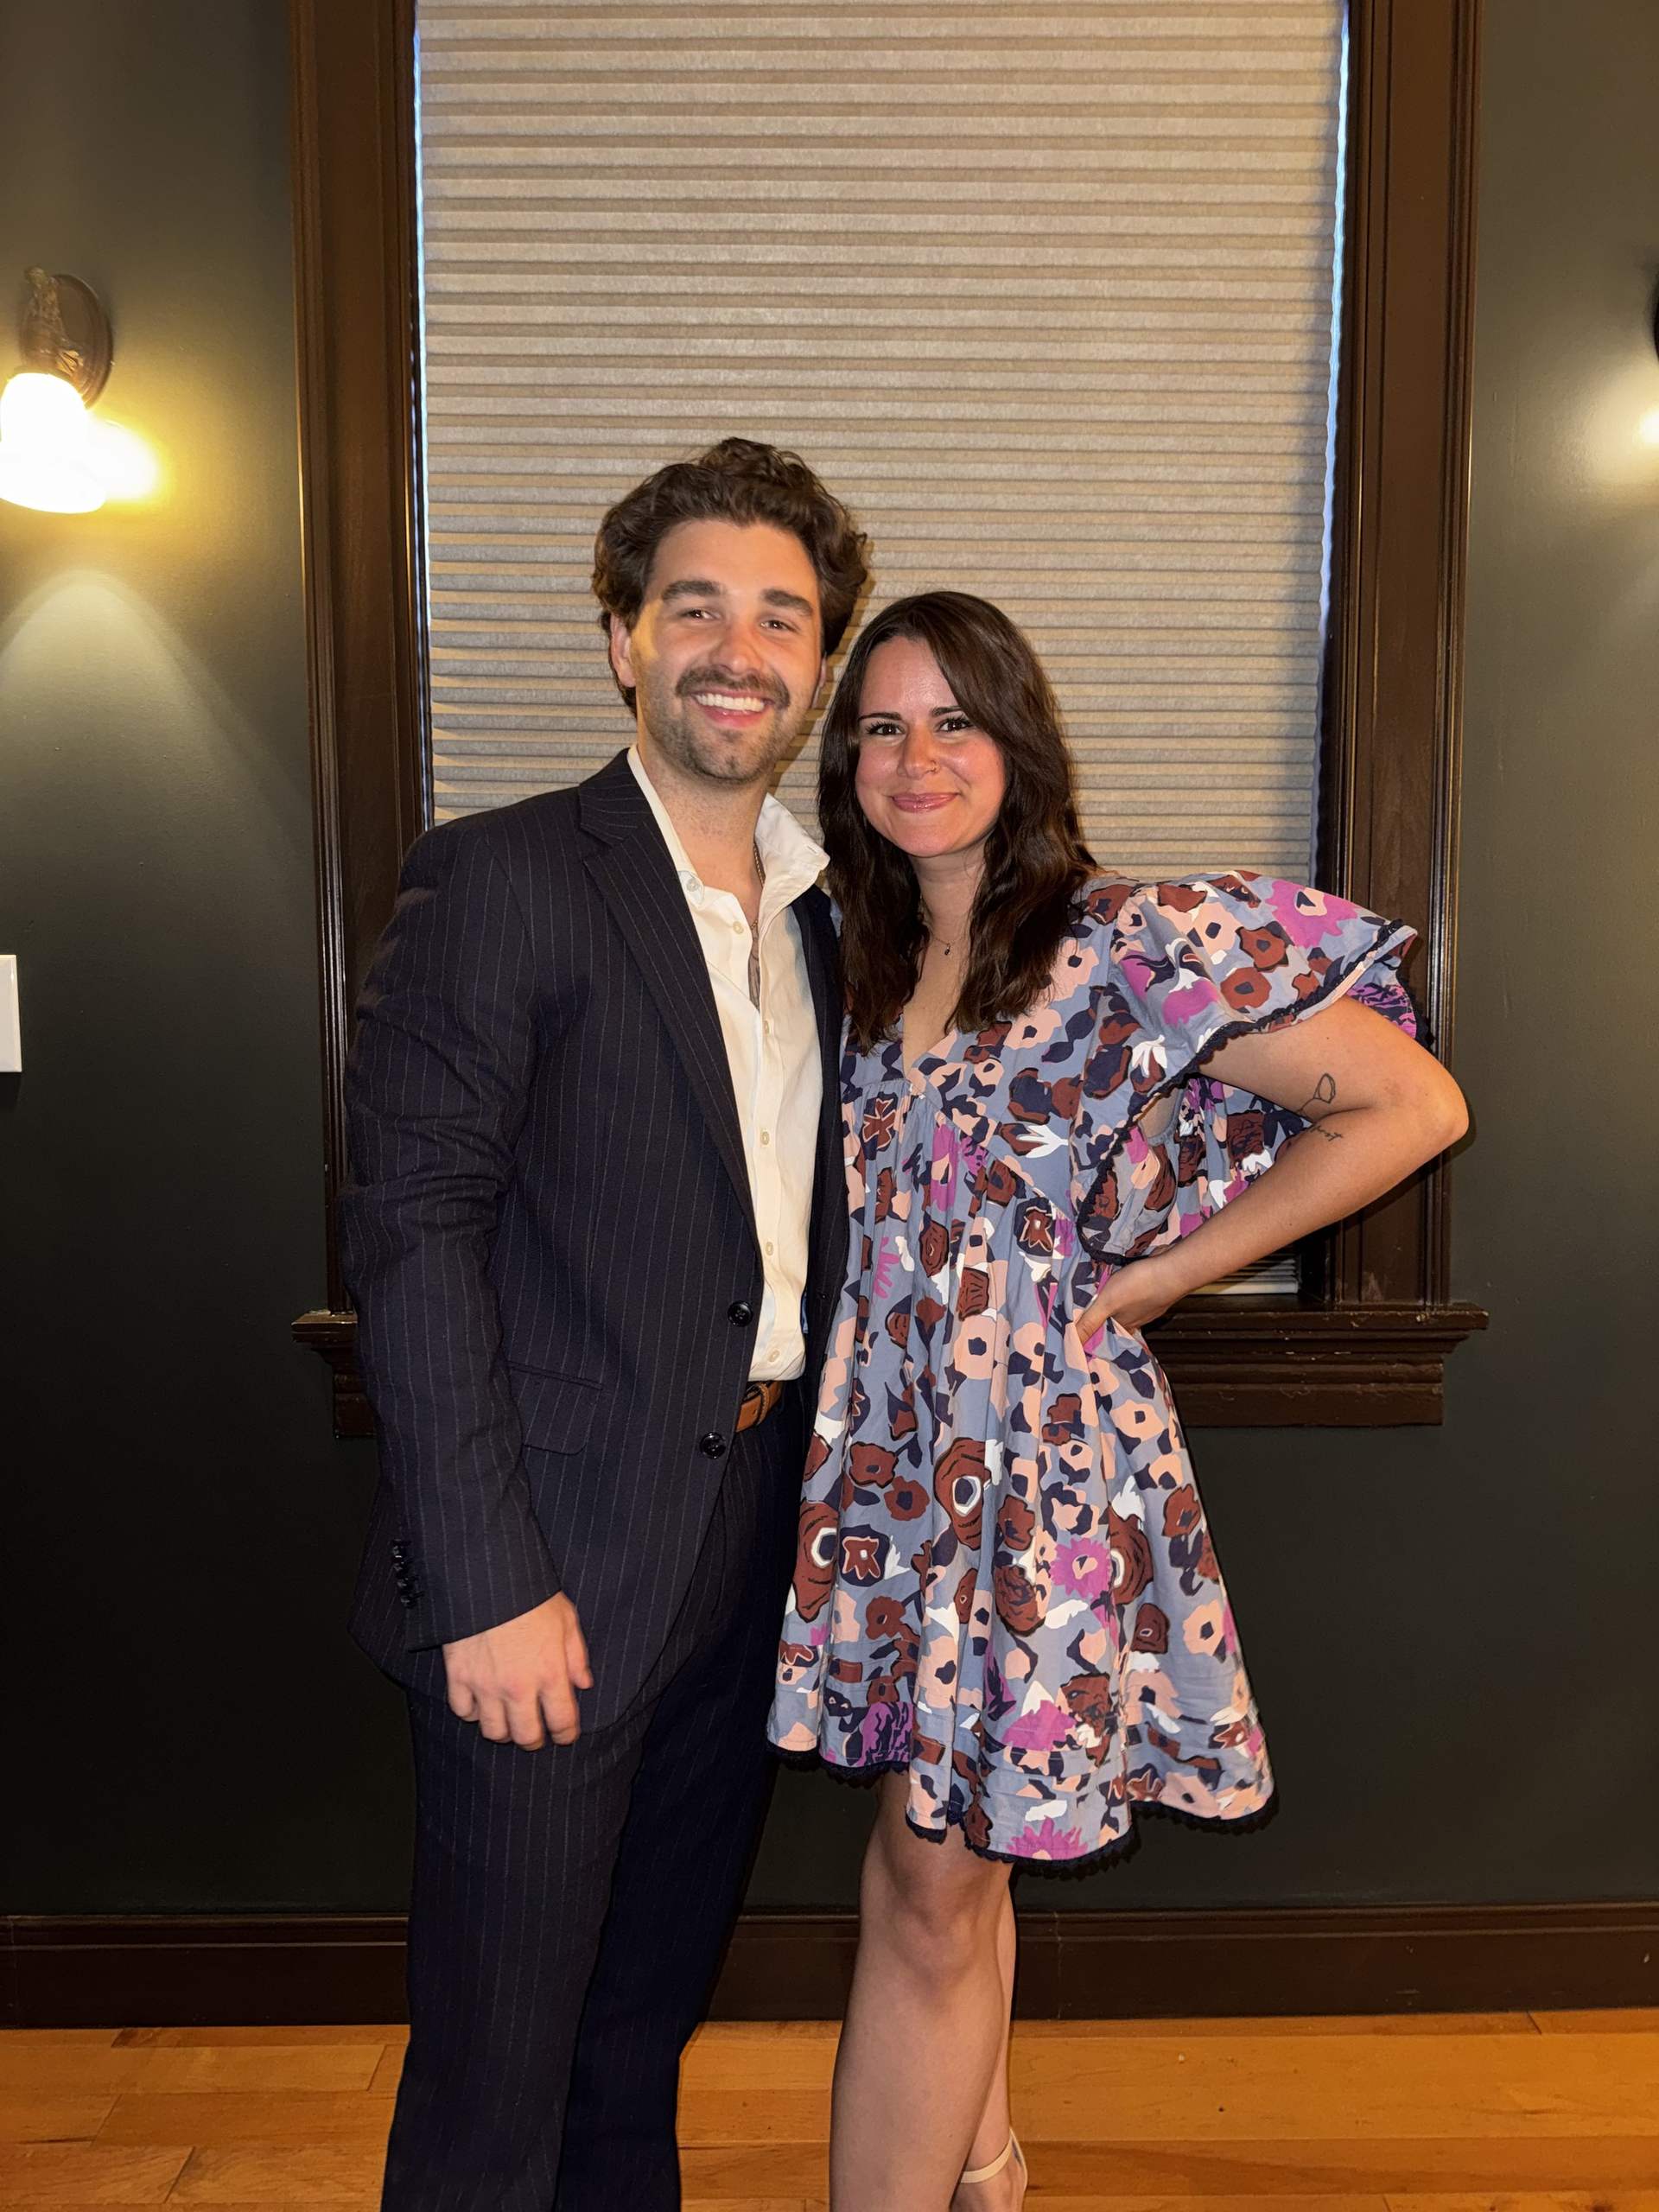
Born and raised in Indianapolis, lending from Carmel
Dillon Baker grew up in Indianapolis and lives in Carmel with his wife and daughter. He is VP of Mortgage Lending at Rate, licensed in Indiana under NMLS #2681440, working from the Rate office at 252 W Main St in Carmel and by text, phone and video with buyers anywhere in the state.
Outside of lending he runs Hive Network, a referral networking group for young professionals across Indianapolis and Hamilton County, and he teaches on YouTube as Loans With Dillon. The teaching is the whole point. "Plain English, no jargon-dropping."
Hamilton County is home ground, Indiana is the license
The whole of Hamilton County is home ground, from Carmel and Fishers up through Westfield, Noblesville and the towns north of them, and Zionsville sits just over the Boone County line. Indianapolis is where he grew up.
Because Rate is licensed statewide, a buyer in Fort Wayne, Bloomington or Evansville works with Dillon the same way a buyer in Carmel does: by text, phone and a video call, with the pre-approval in writing the same day.
Start with a text
Tell Dillon what you're looking to do and where to text you back. It goes to his phone and his email at the same time, he answers himself, and it doesn't pull your credit.
Agent referred buyers under contract get priority, and evenings and weekends count. Offers don't wait for business hours.
Text 317-847-6869 or call, if you would rather skip the form.